CAA 2026 Proposed Rule Summary: Implications for Bona Fide Service Fees & Fair Market Value
Table of contents
On October 16, 2026, Centers for Medicare & Medicaid Services (CMS) issued a proposed rule (CMS-4214-P) implementing the PBM reforms in the Consolidated Appropriations Act, 2026 (CAA 2026). While there are quite a few important aspects to this reform, we have summarized certain items and focused this piece on the aspects relating to bona fide service fees (BFSF) and manufacturer considerations.
Although the rule is directed at Part D sponsors and PBMs, most of the payments it governs come from manufacturers. Manufacturers should consider its implications as well, including how it may spill over into the commercial market. We have already seen PBM fees shift to flat-dollar structures on the commercial side and, more recently, in Part D. As a result, manufacturers are negotiating and reevaluating these arrangements, looking at the appropriate fee structure, whether the services qualify as bona fide services performed on the manufacturer’s behalf, and whether the fees are consistent with fair market value (FMV). We expect this area to continue to evolve, with additional guidance and rulemaking likely to follow.
The Proposed Rule At a Glance: Comments Are Due December 15, 2026
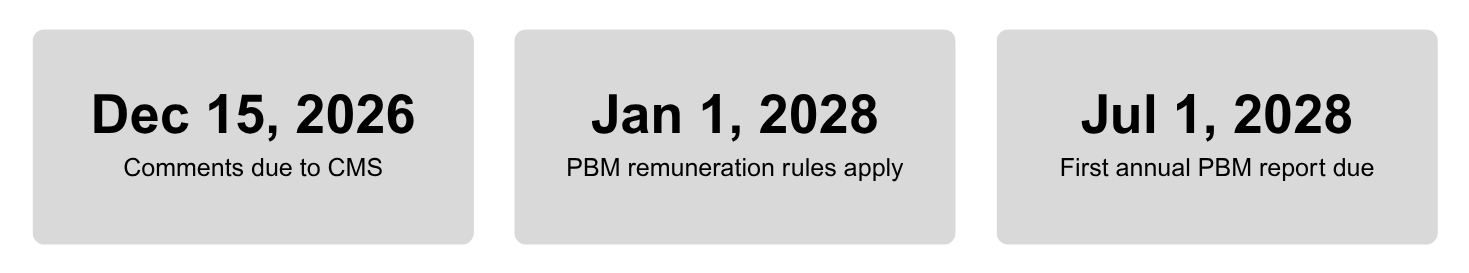
CMS-4214-P, a proposed rule published in the Federal Register on October 20, 2026, would implement three sections of the CAA 2026, which was signed into law on February 3, 2026. Most of the proposed changes would take effect for contract year 2028:
- Section 6219: A $0 generic copay for full-benefit dual eligible at or below 100% of the federal poverty level.
- Section 6220 (REAL Health Providers Act): Verification, accuracy scoring, and public reporting for Medicare Advantage provider directories.
- Section 6224 (PBM accountability): The part that likely matters most to manufacturers, set out in a new Subpart BB of 42 CFR Part 423.
Under Section 6224, from January 1, 2028, a PBM and its affiliates may be paid for Part D drug services only through BFSFs. Manufacturer rebates and other price concessions can still flow, but the sponsor must receive 100% of their gross value. Netting out administrative, data, or aggregation fees is not allowed. Starting in 2028, it would limit Part D PBM compensation to flat, itemized BFSFs. It would also define fair market value for those fees as the cost of the service plus a reasonable markup.
The rule also adds annual PBM reporting to sponsors and CMS (first due July 1, 2028), written explanations of PBM-manufacturer agreements, annual sponsor audit rights, and disgorgement of non-compliant remuneration. Executive-level certifications of compliance round out the enforcement package.
Bona Fide Service Fees: CMS Continues to Focus & Scrutinize This Area
For manufacturers, the BFSF definition has long worked as an exclusion test in government pricing: if a fee meets it, the fee stays out of government pricing calculations (i.e., ASP, AMP, and Best Price). The proposed Part D rule applies the same concept from the other side of the transaction. It doesn’t restrict what manufacturers can pay PBMs; instead, it defines which payments a PBM can treat as compensation for its Part D services. To qualify, a fee must:
- Be a flat dollar amount.
- Pay for an itemized service actually performed.
- Cover a service the payer would otherwise perform or contract for itself.
- Reflect FMV as CMS defines it (cost plus reasonable mark-up).
- Not passed on to a client or customer.
- Not be tied to drug price or a price benchmark (WAC, AWP), rebates or discounts, formulary placement, or the volume or value of business.
The proposal includes several additional provisions. The requirements apply only to the portion of remuneration allocable to Part D utilization. PBMs would be prohibited from requiring an additional fee for access to a service or to the information needed to oversee it. CMS also proposes to prohibit fee methodologies that require the purchase of bundled services.
Fair Market Value: Cost Plus a Reasonable Markup
A central provision of the proposal is proposed § 423.2810(e)(1), which defines FMV for a BFSF as the cost of the itemized service plus a reasonable markup. In other words, a fee is measured against what it costs to provide the service. CMS indicates it would apply established federal cost-reasonableness principles in assessing these costs.
The proposed approach has three notable features:
- A Single Valuation Method: The proposal does not offer a market comparison option for service fees. FMV is based on the PBM’s cost of providing the service, rather than on what the market has historically paid.
- No Independent Valuation Requirement: CMS does not propose to require a third-party valuation, which reduces compliance cost. The parties remain responsible for documenting and supporting the underlying costs, which must be reasonable, allocable, consistent with GAAP and adequately documented. CMS does, however, seek comment on whether any alternative FMV approach should require an independent third-party valuator with no financial stake in the arrangement, so this could change in the final rule.
- A Separate Standard for Incentive Payments: Performance-based incentive payments from a Part D sponsor to a PBM or its affiliate would be treated as BFSFs, provided they are flat dollar amounts, relate to Part D services actually performed, and reflect FMV, assessed against comparable market transactions rather than cost. This treatment does not extend to payments from manufacturers.
CMS acknowledges that the new standards may reduce PBM service fees but states that it lacks the data to estimate the overall impact on Part D. Because Congress, unlike in the PFS context, expressly directed CMS to define FMV through rulemaking. The key open issues for comment are which costs are allowable, how shared and overhead costs are allocated, what constitutes a “reasonable” markup, and who must maintain and produce the cost data.
Implications for Manufacturers: BFSF & FMV
For manufacturers, the proposal raises two central questions: whether each payment to a PBM or its affiliate qualifies as a BFSF, at least for Part D, and whether its amount can be supported as FMV under a cost-based standard.
The BFSF question is where it gets tricky. Under the proposal, a fee is a BFSF only if it meets every one of the criteria above, and CMS continues to question whether certain services are legitimate enough to be paid for at all, much less treated as BFSFs. A fee that falls short cannot be retained by the PBM; it would have to be returned to the plan sponsor. In theory, that may create tension with the manufacturer’s BFSF evaluation for government pricing.
Because the rule applies only to Part D, the more important government pricing consideration for manufacturers is the commercial side. The key question is whether manufacturers will need to apply the Part D standard to their commercial arrangements as well. That would be a significant change, because manufacturers reach different BFSF determinations under current CMS guidance. Until very recently, PBMs largely operated under a traditional model built on percentage-based fees; flat-fee models have only begun to emerge primarily in response to FTC settlements and other pressures. Under the traditional model, many manufacturers treat administrative and/or data fees paid to PBMs as BFSFs, even when those fees are percentage-based, as long as they meet the CMS BFSF test. Whereas some manufacturers treat administrative fees, data fees, or both as non-BFSFs, depending on the facts and circumstances of each arrangement. Given the ambiguity of the BFSF test, and the fact that manufacturers and even PBMs have different needs and different understandings of the services involved, it’s easy to see how these determinations differ.
The FMV question raises a separate valuation issue. CMS defines FMV here as cost plus a reasonable mark-up, but FMV conclusions can vary significantly depending on the approach used, and valuation best practice is generally to consider more than one. A cost-based approach also may not reflect what the market will pay, particularly as AI and other technology lower the cost of delivering services that still carry significant value. Also, in practice sometimes things that are cost based FMV or reimbursed at costs creates incentives for entities to keep costs high versus letting the market forces drive down costs.
Considerations & Next Steps for Manufacturers
The PBM remuneration requirements would apply beginning January 1, 2028, and the rule is still a proposal that may change. Part D bids for 2028 are typically submitted in mid-2027, however, so sponsors and PBMs may begin revisiting contract terms well before the effective date. Manufacturers can prepare now without committing to changes before the rule is final.
- Submit Comments by December 15, 2026: CMS specifically requests comment on its cost and allocation principles, the factors for a reasonable markup, and whether any alternative FMV approach should be allowed. Manufacturers may also wish to address their access to FMV support, the scope of the affiliate definition, and consistency with ASP and Medicaid requirements. Comments are posted publicly.
- Inventory & Classify Current Fees: We recommend inventorying all potential arrangements—not just PBMs—and ensuring you have appropriate BFSF and FMV support. In regards to PBMs specifically, evaluate your current arrangement and each fee paid to these entities under the current guidance and the potential new guidance and work with your legal and government pricing advisors to evaluate impacts and path forward.
- Update Gross-to-Net Models: Build scenarios for Part D fees that move from a percentage of WAC to a flat amount, since those fees would no longer scale with list price increases or volume. Reflect any amounts reclassified from service fees to price concessions in Part D rebate accruals, reserves, and forecasts, and test the effect on 2028 net price and budget assumptions. Whether net revenue changes will depend on negotiated fee levels; presentation in the income statement will depend on each manufacturer’s current accounting policy, confirm treatment with finance and audit teams.
- Evaluate Government Pricing Effects: This proposal amends only the Part C and Part D regulations and may not necessarily change CMS guidance on how manufacturers calculate government pricing. Even so, manufacturers should assess whether restructured fees affect DIR reporting or their own BFSF determinations, document any differences in treatment across programs, and consider the implications for commercial arrangements. The flat-fee concept may be particularly challenging from a government pricing perspective for manufacturers with broad product portfolios, where flat fees may need to be allocated across products.
- Negotiate & Review Contract Language: Work with your legal, government pricing, and business advisors to negotiate contract language that fits your business needs and product portfolio. Pay close attention to how the fee is paid. For example, if a fee is paid per adjusted claim, consider how claims for partial packs are counted, such as a single unit dispensed from a pack of 30. In those cases, the effective fee per unit can vary widely, which can complicate both FMV support and government pricing calculations.
Conclusion
The CAA 2026 proposed rule would significantly change how FMV is determined for PBM compensation in Part D. BFSF would be measured against the cost of the underlying service rather than prevailing market practice, while incentive payments from sponsors would be assessed against comparable market transactions. Although the compliance obligations appear to primarily rest with PBMs and Part D sponsors, manufacturers should expect the effects to surface in contract negotiations, documentation requests, and their own gross-to-net and government pricing analyses.
The rule is limited to Part D, but its implications may extend further. Many PBM, rebate aggregator and GPO agreements span multiple lines of business; CMS acknowledges that PBMs may seek to offset lower Part D fees elsewhere; and the FTC’s proposed consent order with Express Scripts would separately delink manufacturer fees paid to its GPO from drug prices. Manufacturers should therefore consider to review their broader contract portfolio and assess the commercial implications alongside Part D.
Sources
Office of the Federal Register, CMS-4214-P Proposed Rule (Oct. 2026).
Morgan Lewis, “Consolidated Appropriations Act of 2026: The New Landscape of PBM Fiduciary Oversight” (Feb. 2026).
This article is for general information and is not legal advice.
Special thanks to contributor Walt Worsham.
About IntegriChain
IntegriChain delivers biopharma’s only comprehensive data-driven commercialization platform from strategy to operational execution, connecting the commercial, financial, and operational dimensions of drug access and profitability. Our ICyte® Platform integrates technology, data, consulting, and managed services to unify critical workflows replacing manual processes with integrated analytics and precision controls.
Biopharma relies on IntegriChain to optimize patient access and net revenue performance, reduce leakage, and strengthen compliance, ensuring every life-changing therapy reaches patients with speed, affordability, and sustainability. Backed by Nordic Capital, a leading sector-specialized private equity investor with a broad portfolio in healthcare and technology.
IntegriChain is headquartered in Philadelphia, PA, with a location in Pune, India.